Where Bright Smiles Begin.

Does Swiss Health Insurance Cover Root Canal Treatment in Switzerland?
image hero:
Country:
If you have a painful or infected tooth in Switzerland, one of the first questions you may ask is:
Will Swiss health insurance pay for my root canal treatment?
For most patients, the answer is no.
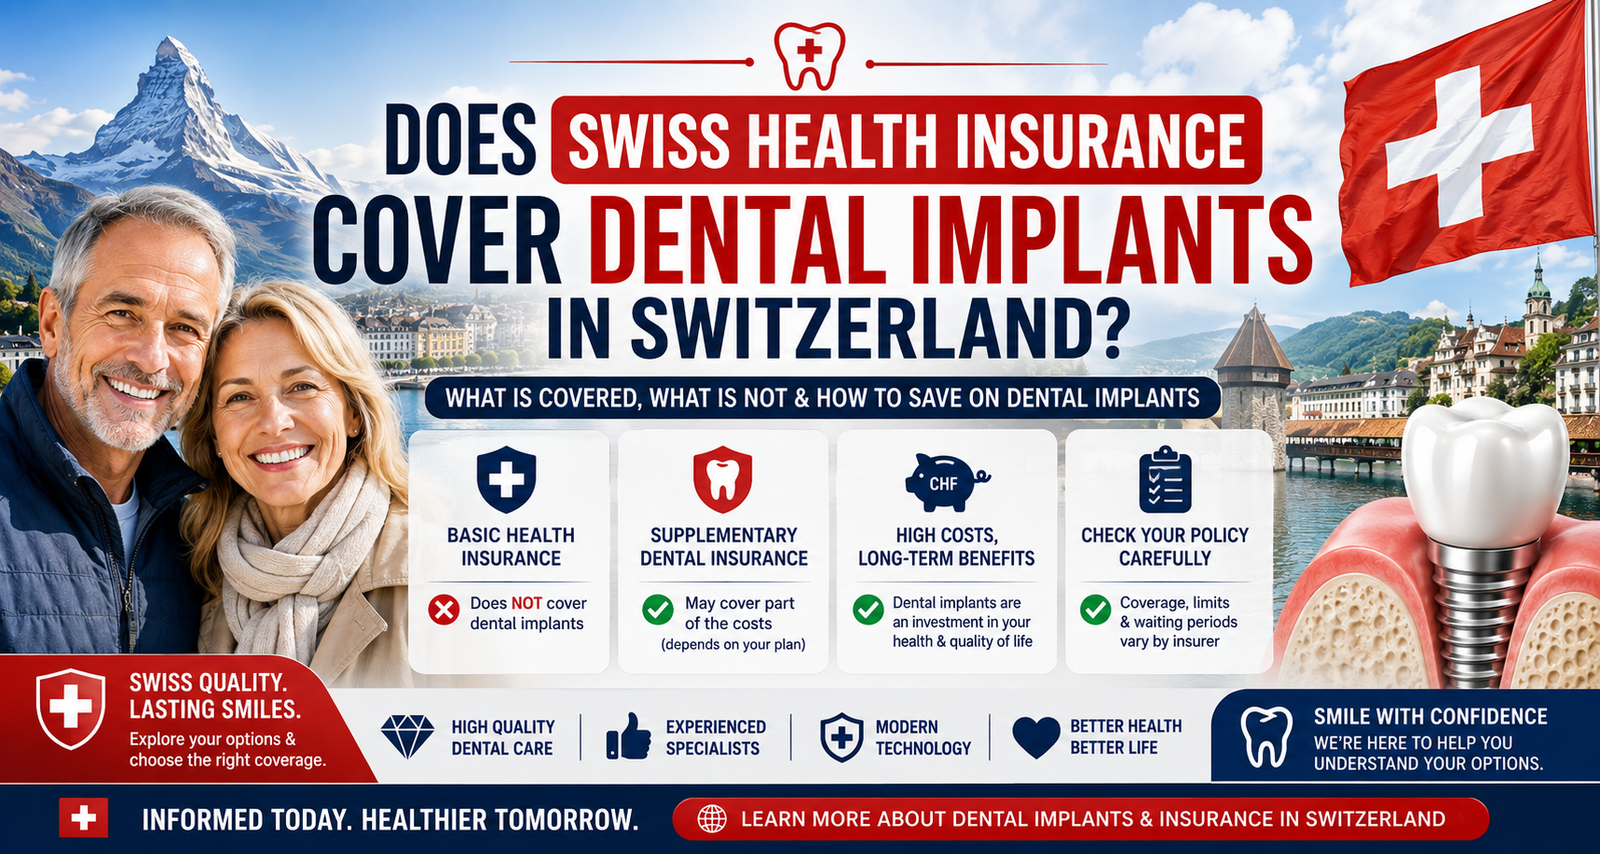
Mandatory basic health insurance under LAMal/KVG generally does not cover ordinary dental treatment, including routine root canal treatment. Patients normally pay for this treatment themselves unless the dental problem falls within specific statutory exceptions.
Because root canal treatment can cost several hundred to more than CHF 1,000 depending on the tooth and complexity, some residents consider supplementary dental insurance (Zahnzusatzversicherung).
However, insurance coverage is highly dependent on the individual policy.
1. Does LAMal/KVG Cover Root Canal Treatment?
Generally, no.
Mandatory Swiss health insurance is designed primarily to cover medical care rather than ordinary dental treatment.
A root canal performed because a tooth has developed ordinary decay or an infection is generally considered dental treatment and is normally paid privately.
This can apply even when the tooth is causing:
-
Severe toothache
-
Sensitivity
-
Swelling
-
An abscess
-
Infection
-
Difficulty chewing
The fact that a dental infection is painful or requires urgent treatment does not automatically make it eligible for reimbursement under basic health insurance.
2. When Can Basic Insurance Cover Dental Treatment?
There are limited statutory exceptions.
Dental Injury From an Accident
If the root canal is necessary because of an accident, coverage may be possible through the applicable accident insurance.
For example, a tooth damaged during a qualifying workplace or sports accident may be treated differently from a tooth that became infected because of decay.
The responsible accident insurer should be contacted to determine whether the treatment qualifies.
Serious General Illness
Certain dental treatments may qualify when they are directly connected to a serious medical condition that meets Swiss statutory requirements.
This can include specific severe systemic illnesses or conditions affecting the jaw and oral structures.
The criteria are narrow.
Simply having a medically significant dental infection does not automatically qualify.
Congenital Conditions
Certain serious congenital abnormalities affecting the jaw or oral structures may also fall under specific statutory provisions.
Eligibility depends on the individual diagnosis and applicable Swiss rules.
3. What Happens When a Tooth Needs a Root Canal?
A root canal can become necessary when the dental pulp inside a tooth becomes irreversibly inflamed or infected.
Common causes include:
-
Deep tooth decay
-
Cracked or fractured teeth
-
Significant trauma
-
Repeated dental procedures
-
Bacterial infection
-
Untreated cavities
The dentist removes the infected or inflamed pulp, cleans and disinfects the root canal system, fills the canals and seals the tooth.
A heavily damaged tooth may subsequently require additional restoration.
4. Root Canal Treatment Is Only Part of the Cost
One of the biggest financial misunderstandings is assuming that the root canal represents the entire treatment.
Depending on the tooth, treatment can involve:
-
Examination
-
X-rays
-
Local anesthesia
-
Emergency treatment
-
Root canal instrumentation
-
Disinfection
-
Root canal filling
-
Temporary filling
-
Post or core, if required
-
Final filling or restoration
-
Crown, if required
A molar with several canals can require substantially more work than a relatively straightforward front-tooth root canal.
Therefore, ask your dentist for an itemized treatment estimate before beginning extensive treatment.
5. How Much Does a Root Canal Cost in Switzerland?
The price varies according to:
-
Tooth location
-
Number of canals
-
Complexity
-
Dentist
-
Treatment time
-
Diagnostic requirements
-
Emergency treatment
-
Whether additional restoration is required
-
Whether a crown is necessary
A straightforward treatment may cost several hundred francs, while complex molar treatment can exceed CHF 1,000.
If a crown is required afterward, the overall cost can become considerably higher.
For this reason, a patient should evaluate the complete treatment plan, not just the root canal fee.
6. Supplementary Dental Insurance
Supplementary dental insurance (Zahnzusatzversicherung) is designed to provide benefits that are not normally included in mandatory basic insurance.
Depending on the product, it may contribute toward:
-
Dental examinations
-
Dental hygiene
-
Fillings
-
Root canal treatment
-
Periodontal treatment
-
Extractions
-
Crowns
-
Bridges
-
Dentures
-
Dental implants
-
Orthodontic treatment
However, the percentage reimbursed and annual maximum differ between policies.
Some plans may reimburse a percentage of eligible dental costs, while others impose specific limits for particular treatments.
7. How Much Could Supplementary Insurance Pay?
Consider a hypothetical example.
Suppose a root canal costs:
CHF 1,000
A policy provides:
75% reimbursement
The theoretical reimbursement is:
CHF 750
The patient's share would be:
CHF 250
But this assumes that:
-
The treatment is eligible.
-
The tooth is not excluded.
-
The waiting period has ended.
-
The annual maximum has not already been reached.
-
Other policy conditions are satisfied.
If the patient has already received CHF 900 in dental reimbursements during the year and the policy has a CHF 1,000 annual limit, the remaining available benefit could be much smaller.
8. Annual Maximums Matter
This is one of the most important things to understand about dental insurance.
A policy might advertise:
75% reimbursement
but also have:
CHF 2,000 annual maximum
That means the insurer does not necessarily pay 75% of unlimited dental expenses.
Imagine a patient has:
-
Root canal: CHF 1,000
-
Crown: CHF 1,800
Total:
CHF 2,800
Even if the policy theoretically reimburses 75%, the annual maximum could restrict the total amount paid by the insurer.
The patient could therefore still have a significant out-of-pocket bill.
9. Pre-Existing Dental Problems
This is particularly important for root canal treatment.
If you already have:
-
Severe toothache
-
A diagnosed infection
-
Deep decay
-
A failing filling
-
A cracked tooth
-
A dentist's recommendation for root canal treatment
you should not assume that purchasing dental insurance afterward will make the treatment covered.
Supplementary insurers may use:
-
Health declarations
-
Dental certificates
-
Dental examinations
-
Underwriting
-
Existing-condition exclusions
An insurer may accept the application while excluding the affected tooth or condition.
In other cases, the application may be declined.
10. Waiting Periods
Supplementary dental insurance may also impose a waiting or qualification period.
Depending on the insurer and product, this can be several months or longer for specific treatments.
A patient who purchases insurance immediately after discovering an infected tooth may therefore discover that:
The policy exists, but the treatment is not yet eligible.
Before purchasing a policy, ask exactly when root canal benefits become available.
11. What Do Patients and Expats Complain About?
Consumer discussions about Swiss dental insurance often highlight several recurring problems.
"I Didn't Know Dental Wasn't Covered"
People arriving from countries where dental insurance is commonly included in broader health coverage can be surprised by Swiss dental bills.
A person may have comprehensive mandatory health insurance and still have to pay privately for a routine root canal.
"The Insurance Percentage Was Misleading"
Consumers sometimes focus on a headline percentage such as 75% without checking the annual maximum.
The actual reimbursement can therefore be considerably lower than expected.
"My Tooth Was Already a Problem"
This is another common frustration.
People may attempt to purchase dental insurance after receiving a diagnosis, only to discover that the affected tooth is considered a pre-existing condition.
"The Root Canal Wasn't the Final Bill"
A root canal may preserve a tooth but leave it structurally weakened.
Depending on the tooth, the dentist may recommend additional restoration.
The total cost can therefore include:
Root canal + restoration + possible crown
rather than just the root canal procedure.
12. Root Canal vs. Extraction
When a tooth has severe infection or structural damage, patients may be presented with different treatment options.
Depending on the clinical situation, these can include:
-
Root canal and restoration
-
Extraction
-
Bridge
-
Partial denture
-
Dental implant
The cheapest initial procedure is not necessarily the cheapest long-term solution.
For example, extracting a tooth may initially cost less than saving it with root canal treatment, but replacing the missing tooth later can introduce additional costs.
The appropriate option depends on the tooth's condition, prognosis, overall oral health and the dentist's assessment.
13. How to Reduce Unexpected Dental Costs
Get an Itemized Kostenvoranschlag
For significant treatment, ask your dentist for a written:
Kostenvoranschlag
This allows you to see the expected cost before treatment begins.
Ask the Insurer Before Treatment
If you have supplementary insurance, send the treatment estimate to the insurer.
Ask specifically:
"What amount will my policy reimburse for this root canal treatment?"
Also ask whether the insurer requires prior approval.
Check Your Remaining Annual Benefit
If you have already claimed dental treatment during the year, determine how much of your annual maximum remains.
Ask Whether the Crown Is Covered
If your tooth requires a crown after the root canal, ask about that treatment separately.
A policy may treat endodontic treatment and prosthetic restoration differently.
14. Swiss Dental Insurance Providers to Compare
When comparing supplementary dental insurance, consumers may encounter products from providers including:
-
SWICA
-
Sanitas
-
CSS
-
AXA
-
KPT
-
Helsana
-
Concordia
-
Groupe Mutuel
Do not select a policy solely because an insurer has positive customer reviews.
Instead, compare the actual contract terms.
Important factors include:
| Factor | What to Check |
|---|---|
| Root canal coverage | Is endodontic treatment included? |
| Reimbursement | What percentage is paid? |
| Annual limit | Maximum CHF reimbursed |
| Waiting period | When coverage begins |
| Existing conditions | Are affected teeth excluded? |
| Dental certificate | Is one required? |
| Crown coverage | Is post-root-canal restoration covered? |
| Orthodontics | Important for families |
| Premium | Monthly and annual cost |
| Treatment abroad | Are foreign dentists eligible? |
15. Should You Buy Dental Insurance?
It depends on your circumstances.
Supplementary dental insurance may make sense if:
-
Your teeth are currently healthy.
-
You want long-term protection.
-
You have children who may need orthodontic treatment.
-
The policy has meaningful annual limits.
-
The premium is reasonable.
-
You understand the exclusions and waiting periods.
It may be less attractive if:
-
You already need a root canal.
-
The affected tooth will be excluded.
-
The annual limit is low.
-
Premiums are expensive.
-
You rarely need dental treatment.
-
You have enough savings to handle dental expenses yourself.
The timing of the purchase is particularly important.
16. What If You Already Have Severe Tooth Pain?
Insurance should not delay necessary dental care.
If you have severe tooth pain, swelling, fever, facial swelling or difficulty swallowing, seek prompt professional dental or medical evaluation.
A dental infection can worsen even if pain temporarily improves.
If an infection is suspected, the dentist can determine whether the appropriate treatment is:
-
Root canal treatment
-
Drainage
-
Extraction
-
Another procedure
The priority should be controlling the underlying dental problem rather than waiting for insurance approval.
17. Final Verdict
For ordinary dental disease, mandatory Swiss basic health insurance generally does not cover root canal treatment.
Coverage may be possible in specific exceptional circumstances, including qualifying accidents or certain serious medical or congenital conditions, subject to Swiss statutory requirements.
For ordinary decay-related root canal treatment, patients should generally expect to pay privately unless they have eligible supplementary dental insurance.
Supplementary insurance can reduce the financial burden, but the details matter:
Reimbursement percentage + annual maximum + waiting period + exclusions + underwriting
are more important than the insurer's advertising headline.
If you already have an infected tooth, don't assume that purchasing insurance now will cover the treatment.
Instead:
Get a dental diagnosis → request a Kostenvoranschlag → check your existing insurance → obtain written confirmation → proceed with appropriate treatment.
Frequently Asked Questions
Does LAMal cover root canal treatment?
Generally, no. Ordinary root canal treatment is normally outside mandatory basic health insurance.
Does supplementary dental insurance cover root canals?
Some supplementary policies may contribute toward root canal treatment. The exact reimbursement depends on the policy.
Can I buy dental insurance after I discover an infected tooth?
You can apply, but the insurer may exclude the affected tooth or decline the application.
How much does a root canal cost in Switzerland?
Costs vary according to the tooth and complexity. Treatment can range from several hundred francs to more than CHF 1,000, with additional restoration potentially increasing the total.
Does insurance cover the crown after a root canal?
It depends on the policy. Crowns may have different coverage rules and limits from endodontic treatment.
How long is the waiting period for dental insurance?
It varies by insurer and policy. Several months is common, but certain treatments can have different qualification periods.
Can a root canal after an accident be covered?
Potentially. If the treatment results from a qualifying accident, accident insurance may be responsible for the dental costs.
Should I get dental insurance before I need treatment?
If you want protection against future dental expenses, investigating supplementary coverage while your dental health is good is generally more useful than waiting until a problem has already been diagnosed.
Disclaimer
Swiss insurance products, premiums, coverage rules, exclusions and waiting periods can change. This article is for general educational purposes and is not insurance, financial or medical advice. Confirm current coverage directly with your insurer and obtain written confirmation before relying on insurance reimbursement for expensive dental treatment.
Last reviewed: August 2026
Related Clinical Cases
Patients with lower front gum inflammation may also experience tartar buildup, periodontal disease, gum abscesses, or tooth decay. Explore these related clinical case studies.
Other topics:
Other Dental Clinic